• Skip to primary navigation
  • Skip to main content
Collective

Collective

A blog to help freelancers with taxes - Collective

What we offer

Business setup Form your business the right way Accounting Expert approved, powered by AI Invoicing Get paid faster, without the busywork Payroll Payroll made simple for S Corps Taxes Stress-free taxes for solopreneurs Business insurance Coverage for your business Health insurance Instant and affordable health coverage Support Human expertise + AI speed
Pricing Customers
About us Partnerships Careers We're hiring! Press
Blog Newsletter Webinars

Free tools

S Corp tax savings calculator Estimated tax & extension calculator Tax calendar S Corp admin cost calculator Freelance rate calculator Bill rate calculator
See all free tools →
Login
Business setup Accounting Invoicing Payroll Taxes Business insurance Health insurance Support
Pricing
Customers
About us Partnerships Careers We're hiring! Press
Blog Newsletter Webinars S Corp tax savings calculator Estimated tax & extension calculator Tax calendar S Corp admin cost calculator Freelance rate calculator Bill rate calculator See all free tools
Login
Resources / Money Management · 4 min read

How to Use your Personal Financial Identity to Grow your Business

Unlock growth potential by leveraging your personal financial identity. Learn how to align it with your business strategy for maximum success.

Man on laptop with his child next to him. Child is on playing on phone. Both are wearing white t-shirts
Keisha Blair
Written by Keisha Blair
Eric Poole
Updated by Eric Poole
Published Feb 2, 2021 · Last updated May 22, 2024
On this page 5 sections
  1. For the Minimalist
  2. For the Maximalist
  3. For the Risk-Taker
  4. For the Anxious Spender
  5. Regardless of your personal financial identity, you can Succeed as a Business-of-One

AI Summary

AI-generated from this article. Not tax advice.

  • The Minimalist can scale with a lean-startup mentality and should streamline offerings, noting that roughly 20% of services may deliver 80% of income.
  • The Maximalist brings fearless, energetic ideas but risks overspending, debt, and procrastination, and benefits from an accountability partner and close expense tracking.
  • The Risk-Taker is driven and creative but tends to become over-leveraged and should keep monitoring debt.
  • The Anxious Spender can suffer analysis paralysis and benefits from setting deadlines and pairing with a bolder accountability partner.
Table scrolls sideways →

On your self-employed journey, there may be issues and roadblocks that affect the speed with which you scale your business. Understanding how to harness the strengths and weaknesses of your financial identity can help pinpoint the issues and illuminate what might be slowing you down.

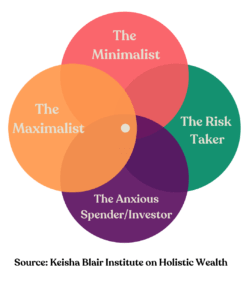
In the first and second articles in this series, I offered a primer on the Personal Financial Identities Framework that I developed, with information on each type and a quiz to reveal your financial identity. Here’s a quick diagram outlining the four personal financial identities:
For the Minimalist

Your mantra of simple living to its core is readily applicable to your business decisions, including automating and streamlining, how you interact with your clients and fine-tuning your core product offering. 

With minimalism in business, you’ll want to develop a business mission that eliminates time-consuming detours and “shiny new object syndrome.” Figuring out which offerings yield the most profitable outcomes (in terms of time and money) will deliver the most benefit to you, and you’ll avoid getting bogged down with multiple offerings that are time-consuming and yield low returns. 

If you analyze all of your services and products and realize that only 20% deliver 80% of your income, then it’s time to streamline even further.

Advantages of the Minimalist:

  • Does not rely on debt to finance business
  • Can scale faster with a “lean-start-up mentality”
  • Less likely to succumb to “shiny new object syndrome”

Disadvantages of the Minimalist:

  • May overlook some great business opportunities
  • Tends to take on less measured risks 

For the Maximalist

Your mantra of “Go big, or go home” and your larger than life perspective on opportunities can be beneficial in business. You tend to be fearless, energetic with bold business ideas and a passion for innovation. 

However, your tendency to want all (and often the priciest) bells and whistles can result in a loss of income before you even launch or have an opportunity to scale. While you may want a stunning website and a home office worthy of Architecture Digest – that doesn’t necessarily translate into profitability. 

This could not only lead to significant expenses (as well as debt) but also perfectionism and procrastination in launching and scaling your business, missing out on “first-mover advantage” that’s so critical in a rapidly changing world. One important tactic for the Maximalist is accountability (find an accountability partner) and a budget and track your expenses closely.

Advantage of the Maximalist: Fearless, and energetic with a wealth of business ideas.

Disadvantage of the Maximalist: Tendency to take on more risk, debt and succumb to shiny-object syndrome because of inner and outward expectations. 

Get help with your self-employed business

For the Risk-Taker

You’re always on the lookout for the next business deal or investment – you can’t wait to wrap this one up because you heard about the new start-up that has a trendy new product.

However, with this tendency, you may become over-leveraged or go into debt. Continue to monitor your debt and ensure you don’t become too financially overcommitted. Also, get an accountability partner (like the Minimalist), as you continue your quest for world domination.

Advantages of the Risk-Taker: 

  • Driven to learn new skills
  • Highly empowered to break through self-imposed limits
  • Highly creative
  • Has a clear sense of desires and breaks free from being just average in business

Disadvantage of the Risk-Taker: 

  • Tendency to become over-leveraged (with business or investment loans) and take on more debt

For the Anxious Spender

Anxious Spenders can suffer from “analysis paralysis,” endless research and anxiety and worry about their money decisions. In order to overcome this problem, Anxious Spenders can give themselves a deadline or set limits when it comes to business decisions. 

Another tactic is to find an accountability partner – the Risk-Taker may be a great partner for the Anxious Spender, due to their bold, courageous nature.

Advantages of the Anxious Spender: 

  • Tendency to avoid money or business risks or mistakes
  • Tendency allows for taking the time to discover their full potential

Disadvantages of the Anxious Spender:

  • May overlook some beneficial business and investment opportunities
  • Tends to take on less measured risks

Regardless of your personal financial identity, you can Succeed as a Business-of-One

Once you know what your personal obstacles are, it’s much easier to figure out a quick and easy solution to solve them.

As our world continues to change, we’ll need to get more sophisticated and self-aware about our financial identity and spending and savings habits to be more successful with our money and businesses. After COVID-19, most people will be reassessing their priorities and self-knowledge will be key. Goodbye to these “one size fits all” money rules. Moving forward, tailored solutions that fit our personal financial identities will be key to success.

Take the free quiz, if you haven’t yet, and then take the Personal Financial Identities Online Course in order to understand your personal financial identity for better success.

Our website contains general information only and this information is not to be taken as legal, tax, or financial advice. You should consult with your attorney and/or tax advisor to get answers to your specific questions.

Get help with your self-employed business

Collective handles the tax and accounting side of your business – so you have more time to focus on your passion. LLC formation, S Corp election, bookkeeping, monthly financial reporting and an average member tax savings of $10,000*.

Get Started

More on Money Management

All Money Management posts
Blog

S Corp Financial Management: A Plain-Language Guide for Solopreneurs

You set out to do your craft, not to run payroll and chase tax…

Aug 25, 2026 · 7 min read
Money Management

Best Business Bank Accounts for Solopreneurs in 2026

Your business income and your grocery budget don’t belong in the same account. The…

Aug 19, 2026 · 11 min read
Money Management

Payroll Solutions for Solopreneurs: A Comparison Guide

When you make an S Corp election, running payroll becomes part of your required…

Apr 30, 2026 · 4 min read
Blog

How S Corp Owners Navigate Mortgage Approval

One of the most persistent anxieties in self-employment is the mortgage question. Will lenders…

Apr 8, 2026 · 4 min read
Blog

Retirement Plans for S Corp Owners

Intro to Retirement Plans The perks of owning your own business are bountiful but…

Dec 10, 2024 · 2 min read
Blog

What is Payroll?

TL/DR Version Payroll is the process of managing wages, salaries, and taxes for your…

Aug 18, 2023 · 12 min read
Money Management

4 Retirement Savings Options For The Self-Employed

Retirement accounts are important for anyone who wants to retire someday. When you work…

Sep 14, 2021 · 6 min read
Blog

5 Personal Finance Best Practices for Six-Figure Business Owners

You must be doing something right since your business is scaling to the multi-six…

Aug 13, 2021 · 6 min read
Blog

How to Account for Health Insurance, Vacation Time and Other Benefits in your Hourly Rate

The topic of insurance and “benefits” as a full-time freelancer is one that both…

Jun 3, 2021 · 5 min read
Blog

How to Save When You’re Self-Employed and have Inconsistent Income

Dr. Martin Luther King Jr. is believed to be the first to introduce the…

Apr 27, 2021 · 7 min read
Blog

How to pay yourself when you’re self-employed

Payday — these words can sound like music to your ears. After all, you’ve…

Apr 1, 2021 · 6 min read
Blog

How to Run Payroll for an S Corp

You don’t need to be a business with a bunch of employees to run…

Mar 11, 2021 · 4 min read
Blog

9 Reflection Questions to Help Your Business Level Up Next Year

As a busy business owner, you’re probably concerned about looking towards the future. After…

Dec 8, 2020 · 7 min read
Blog

How the 80/20 Rule Helped me 3x my Revenue in Less than a Year

If you don’t have a finance or accounting background, it may not always be…

Oct 26, 2020 · 5 min read
Blog

How to Create an Authentic Budget for Your Business

When it comes to creating a budget for your business, there’s more than one…

Sep 7, 2020 · 7 min read
Blog

Create a Better Business Using Values-Based Spending

Whether you’re just starting out or have been freelancing for years, the question of…

Aug 31, 2020 · 7 min read
Blog

Level Up Your Freelance Finances with These Expert Tips

When you first started your business, you probably put some effort into your finances.…

May 15, 2019 · 5 min read
Blog

How to Pay Yourself When You’re a Freelancer

Whether you’re first starting out as a freelancer or you’re a self-employed freelancer who’s…

Jan 29, 2019 · 9 min read
Blog

How Much Should You Pay Yourself? S Corp Salary Guide for Freelancers

Many Business-of-One owners with an LLC elect S Corp tax treatment because of the…

Jan 24, 2019 · 14 min read
Blog

How to Open a Business Bank Account for Your New Business

Starting a new business is an exciting time with so much potential in the…

Jul 26, 2018 · 8 min read

About the author

Keisha Blair

Keisha Blair

Keisha Blair is the bestselling author of Holistic Wealth: 32 Life Lessons To Help You Find Purpose, Prosperity and Happiness and founder of the Keisha Blair Institute on Holistic Wealth, which offers the Certified Holistic Wealth Consultant Program for entrepreneurs and professionals. Her work has been featured in The New York Times, Forbes, The Wall Street Journal, Harvard Business Review, and Yahoo Finance. Find more at www.keishablair.com.

All articles by Keisha

Best for S Corp owners

Payroll, books and filings in one membership

LLC Tier $199/mo · S Corp Tier $349/mo

Related

  • S Corp Financial Management: A Plain-Language Guide for Solopreneurs
  • Best Business Bank Accounts for Solopreneurs in 2026
  • Payroll Solutions for Solopreneurs: A Comparison Guide

Latest

  • A New Era of Entrepreneurship
  • Collective Raises $100M for Full Stack AI Financial OS Powering the Solopreneur Revolution
  • The Vampire Expenses Draining Your Business

We’re glad you’re here!

First, tell us about your business

Net profit = Total revenue - total expenses

  1. Find total revenue. Add up all money your business earned from sales of goods or services during the year.
  2. Subtract your expenses. Deduct all business costs like supplies, rent, utilities, software, contractor payments, and loan interest.

An estimate is fine, you don't need exact figures.

W2 employees are people on your payroll

You withhold income tax, Social Security, and Medicare from their paychecks, and they get a W-2 form from you at the end of the year.

Don't count yourself (even if you pay yourself a salary) or 1099 contractors and freelancers.

I agree to Collective Terms of Service & Privacy Policy. Additionally, by providing phone number to continue, I agree to receive calls, incl. autodialed or prerecorded sales calls, from Collective.

Collective logo

We are experts in the unique needs and challenges of self-employed people and know that our confidence gives others confidence, too. Reach out to say hello and join our team.

We are experts in the unique needs and challenges of self-employed people and know that our confidence gives others confidence, too. Reach out to say hello and join our team.

Products

  • Business setup
  • Accounting
  • Invoicing
  • Payroll
  • Taxes
  • Business insurance
  • Health insurance
  • Support
  • Late S Corp election

Company

  • Home
  • Pricing
  • About us
  • Careers
  • Contact us
  • Partnerships

Resources

  • Blog
  • Guides
  • Help center
  • Testimonials
  • Press
  • Create with us

Legal/Support

  • FAQ
  • Terms of service
  • Privacy policy
  • Security policy

Compare

  • Compare all
  • Collective vs Lettuce
  • Collective vs LegalZoom
  • Collective vs TurboTax
  • Collective vs ZenBusiness

Collective provides a suite of tools, back-office support, and general information. Our services are not intended as tax, legal, or professional advice.

* Savings estimates reflect the average 2023 federal self-employment (SE) tax savings for Collective members with an S Corp tax election, based on business profits that would've otherwise been subject to SE tax. Actual savings will vary based on individual circumstances.

** Based on data sourced from Shopify blog, QBO Essentials, QBO Live, Gusto, Taxfyle, Intuit "Tax Pro" Research, LegalZoom and JustAnswer.com as of August 2025.

† Individual tax return packages are billed as an annual, one-time add-on fee.

© 2026 Collective Hub, Inc. All rights reserved